What Types of Insurance Should a Digital Marketing Agency Have?

December 27, 2017

Professional Liability is An Important Risk to Consider

One of the greatest exposures a professional working in a service industry such as a marketing consultant falls under the label of professional liability losses. “ Professional liability ”, sometimes called “errors and omissions” coverage can come into play for losses related to malpractice or misrepresentation:

  • Libel of a client’s competitor
  • Slander of a client’s competitor
  • Poor marketing advice that results in damages to a client
  • Unethical information/survey gathering
As with any other business it is also advisable to purchase: Depending on whether or not you have a business location and employees, the need for : There are other coverage needs that can come into play in addition to those outlined. Check with a professional Independent Insurance Agent in your area that specializes in Commercial Insurance. You can find one using the Trusted Choice Agent Locator .


-------------------------------

“Ask Jeff" is a weekly post made on the RyanAgency.com Blog. 

Submit an insurance-related question to “Ask Jeff”. 

-------------------------------

This article may have been originally published at Quora.com.

To see Jeff's Quora.com profile click here.

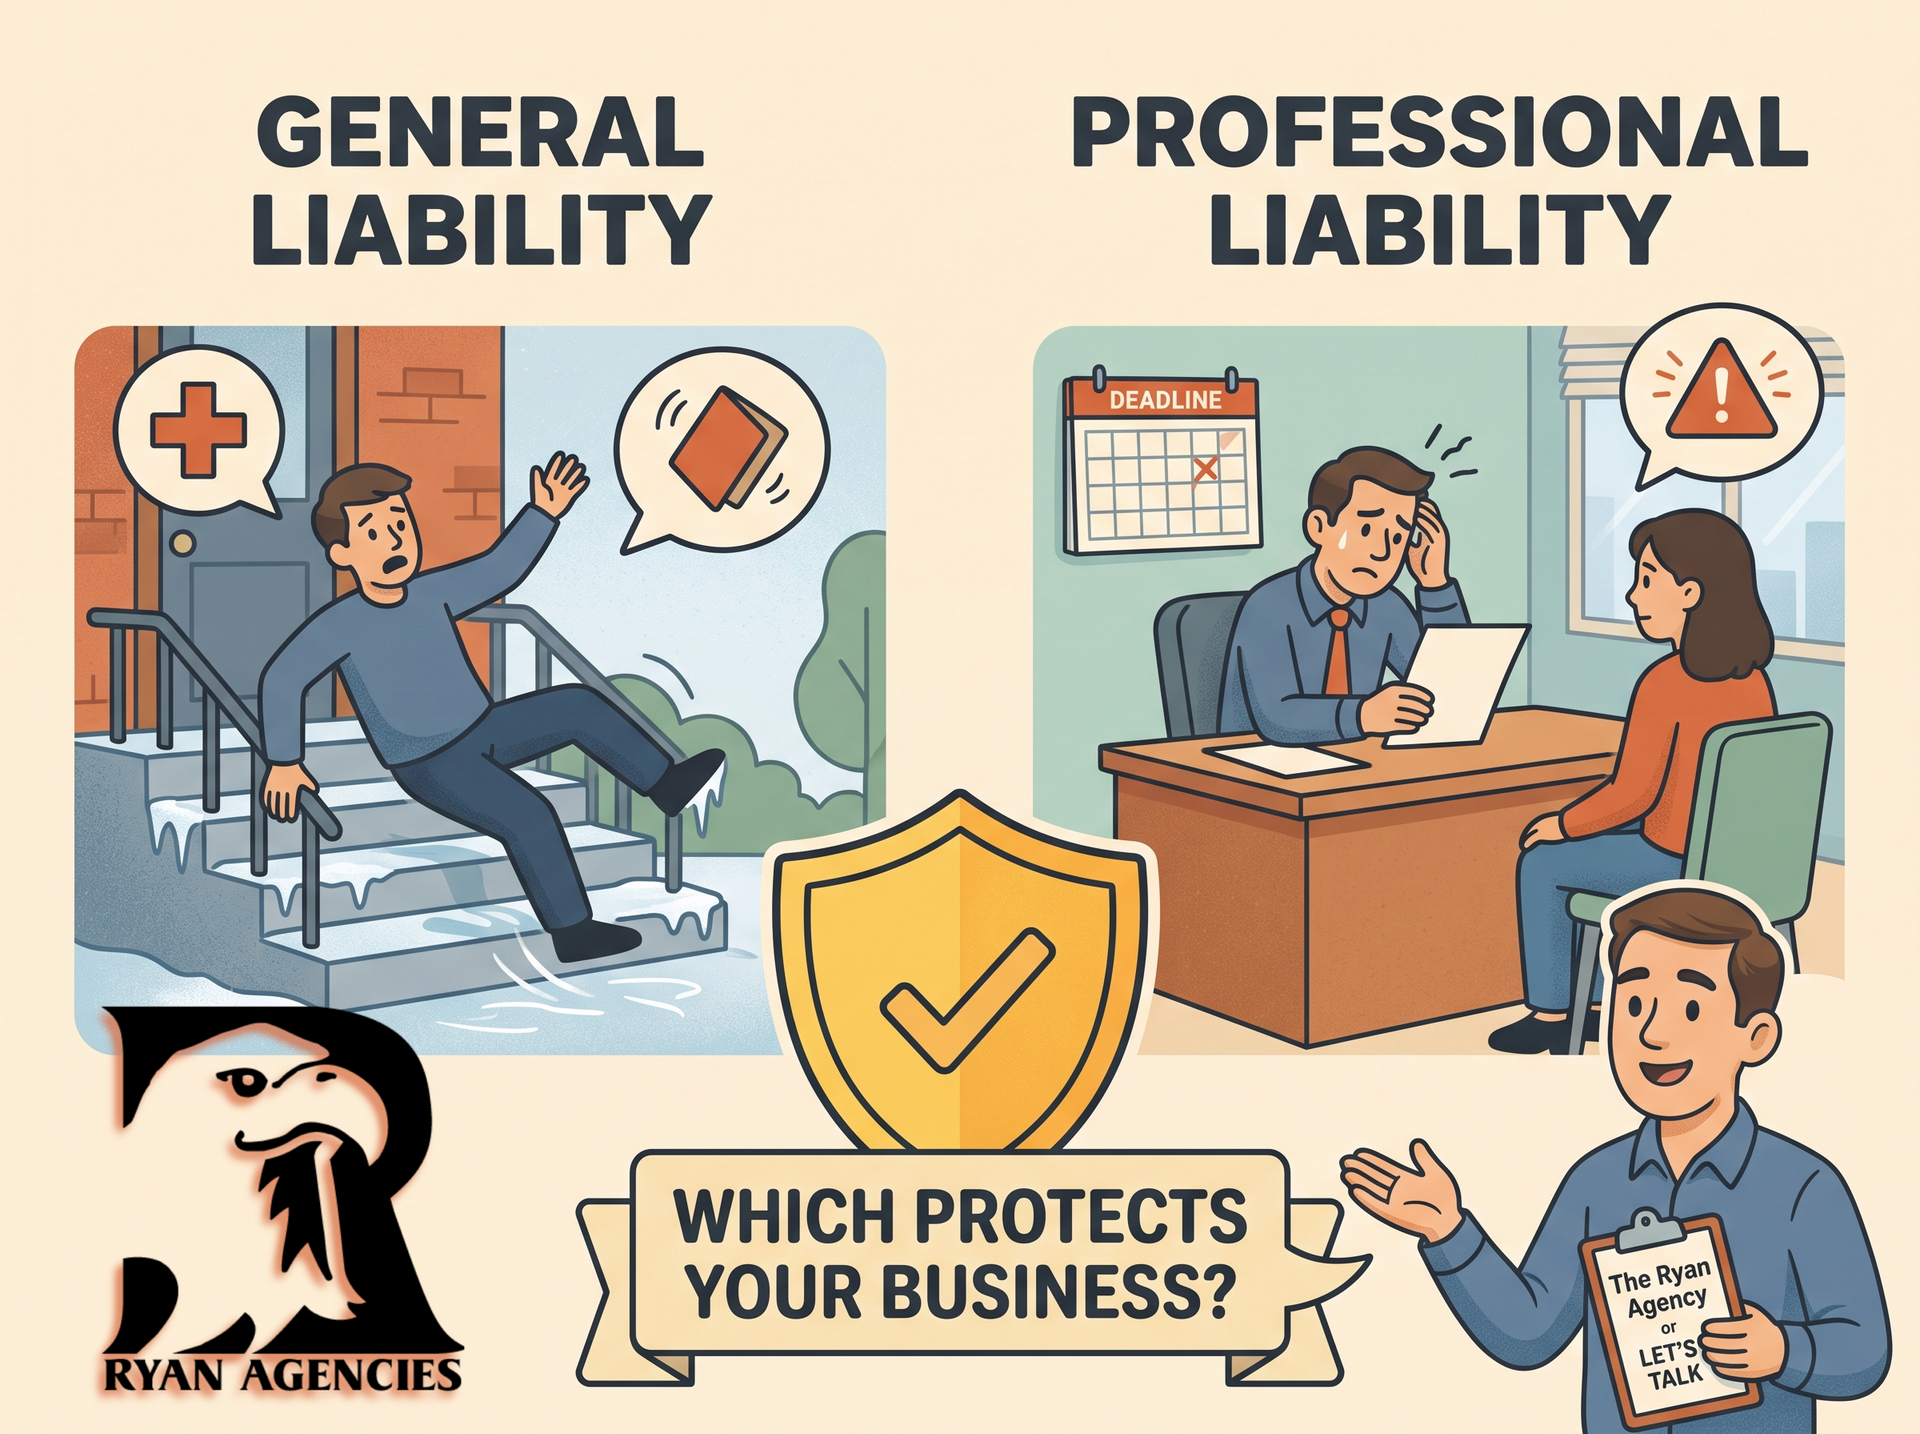
General Liability vs. Professional Liability: Which Protects Your Business?
By Jeff Ryan • October 27, 2026
Protecting your small business means guarding both your physical storefront and professional reputation. Here is how General Liability and Professional Liability work together under New York law to keep you secure.
Preparing for a new driver? Let's Build Insurance Value Together!
By Jeff Ryan • October 20, 2026
Preparing for a new driver? Let's Build Insurance Value Together!
By Jeff Ryan • August 20, 2026
Homeowners: Value Beyond the Basics Mini-Series
How a Vanishing Deductible Can Unlock Long-Term Premium Savings
By Jeff Ryan • June 9, 2026
How a Vanishing Deductible Can Unlock Long-Term Premium Savings with a Simple Change
By Jeff Ryan • April 7, 2026
Factors You Can’t Easily Control These factors are built into your profile, but still play a major role: Your location: Claim trends, traffic, and weather patterns where you principally drive. Your age and driving experience: Especially for younger drivers. Other drivers in your household: Their age and driving history. The vehicle you own: Unique to the Year, Make, Model, and Sub-model’s damageability and cost of parts/labor. These factors significantly influence price differences, but they don’t tell the whole story. Factors You Can Control This is where habits and wise decisions can make a real difference: Your driving habits: Minimizing tickets and accidents can have a direct impact. Your coverage choices: Liability limits, deductibles, and optional coverages can vary widely. Your insurance consistency: Avoiding lapses in coverage. Your annual mileage: How much and how often you drive. Discount opportunities: Bundling, pay-in-full, NYS defensive driving course. Your Insurance Score (Yes—You Can Influence It) Insurance companies use a credit-based insurance score as part of their rating process. While it’s based on financial behaviors, it is not permanent—and it can be improved over time. Simple habits like: Paying bills on time Reducing outstanding debt Avoiding excessive credit inquiries… can positively impact your score—and in turn, your insurance rates. Your insurance score is under your control and a worthy mid to long-term project in and of itself. For more information on what you can do to positively influence your score, see: Great 8 Tip #8 - What's Credit Got to Do with Insurance? How Can I Improve My Auto Insurance Score Why Comparing Rates Doesn’t Work When someone says, “I only pay…” , the uniqueness of their fingerprint is missing. What are their: Deductibles Driving history Insurance score Household profile Coverage limits: what they may be giving up in terms of protection. Price without context can be misleading and discouraging.
By Jeff Ryan - CLU, ChFC, AIA, CIC, CPCU • December 7, 2025
Part 7 – Designing a Value-Driven Insurance Plan
By Jeff Ryan - CLU, ChFC, AIA, CIC, CPCU • November 24, 2025
Part 6 – Advice, Advocacy, and Answers
By Jeff Ryan - CLU, ChFC, AIA, CIC, CPCU • November 12, 2025
Part 5 – Can Your Company Deliver?
By Jeff Ryan - CLU, ChFC, AIA, CIC, CPCU • October 29, 2025
Part 4 – Custom Coverage = Real Protection
By Jeff Ryan - CLU, ChFC, AIA, CIC, CPCU • October 15, 2025
Part 3: Coverage Limits - "The Ceiling You Don't Want to Collapse"